When Is a Credit Card Annual Fee Actually Worth It?
A credit card annual fee gets a lot of attention. If you're paying $95, $250, or considerably more each year just to keep a card open, it's fair to ask whether that card is actually worth it.
But I think this is where people can evaluate cards too quickly.
A high annual fee does not automatically make a card a bad deal. And a low annual fee does not automatically make a card a good one.
The better question is:
What are you actually getting for that fee, and would you still choose to pay it today?
Start With What You Genuinely Use
The easiest way to overvalue a credit card is to count every listed perk as if it gives you full value.
If a card offers credits or benefits that fit spending you were already going to do, those can help justify the fee. But if you have to change your habits, spend more, or track a long list of small credits just to use them, the value may be much lower than it looks on paper.
I would start by asking:
What benefits did I actually use?
Which ones fit my normal habits?
Which ones sounded good when I opened the card but did not matter in practice?
Not Every Credit Is Worth Face Value
A card may offer hundreds of dollars in statement credits, but that does not automatically mean you're receiving hundreds of dollars in real value.
A $100 credit is worth close to $100 if you were already going to make that purchase anyway. It may be worth much less if you have to change where you shop, spend more to use it, or would never have bought the product or service without the credit.
That does not make the benefit useless. It just means you should value it honestly.
Some Benefits Don't Come With a Neat Dollar Value
Statement credits are relatively easy to evaluate. Other benefits are harder to put a number on.
Depending on the card, those might include airport lounge access, purchase protections, extended warranty coverage, travel protections, hotel benefits, rental-car benefits, or other perks.
Take airport lounge access. One person may travel frequently and use a lounge almost every time they fly. If a lounge visit would otherwise cost around $50, that access could represent meaningful value over a year.
Another person may have the exact same card and only visit a lounge once or twice.
The benefit is the same. The value is not.
Purchase protections and extended warranties are different because you may not use them every year. That does not make them worthless. If those protections affect which card you use for larger purchases, they can be a legitimate reason the card earns a place in your wallet.
The important thing is not to invent a dollar value just to make the annual-fee math work.
Instead, ask:
Do I actually use this benefit?
Would I pay for something similar without the card?
Does it change which card I use for certain purchases?
Do I already receive something similar from another card?
Two people can have the exact same premium card and come to completely different conclusions about whether its annual fee is worth paying. That's normal. The value is personal.
Rewards Matter, But They Aren't the Whole Story
Rewards can absolutely be part of the equation.
If a card helps you earn stronger rewards in categories where you're already spending, that can add meaningful value. The same is true if the points or miles support travel goals you actually have, or if cash back gives you a better return on spending that was already going to happen.
But a card is not automatically worth keeping just because it earns good rewards.
I would also ask:
Does this card fill an important role in my wallet?
Am I using it enough for that role to matter?
Does another card I already have do something very similar?
Look at the Whole Wallet
A credit card should not be evaluated in isolation. It should be evaluated alongside the cards you already have.
Maybe one card gives you lounge access, and another one does too. Maybe multiple cards provide similar travel protections. Maybe a card that made sense when you were traveling frequently no longer fits the way you spend today.
Or maybe you opened a card for a strong welcome offer and several years later you are still paying the annual fee without asking what the card is doing for you now.
This is where strategic spending matters. The goal is to understand how the cards you already have work together, where your money is going, and whether each card still serves a useful role.
One of my favorite questions to ask is:
If I did not already have this card, would I choose to apply for it again today at its current annual fee?
If the answer is no, I would want to understand why.
Don't Forget the Cost of Complexity
A wallet with several premium cards may require you to remember multiple credits, benefit deadlines, earning categories, travel perks, and annual fees.
For someone who enjoys managing that, the complexity may not be a problem. For someone else, a theoretically valuable card can become less valuable because using all of its benefits feels like another job.
The goal is not to squeeze every possible dollar out of every card. The goal is to build a setup you will actually use.
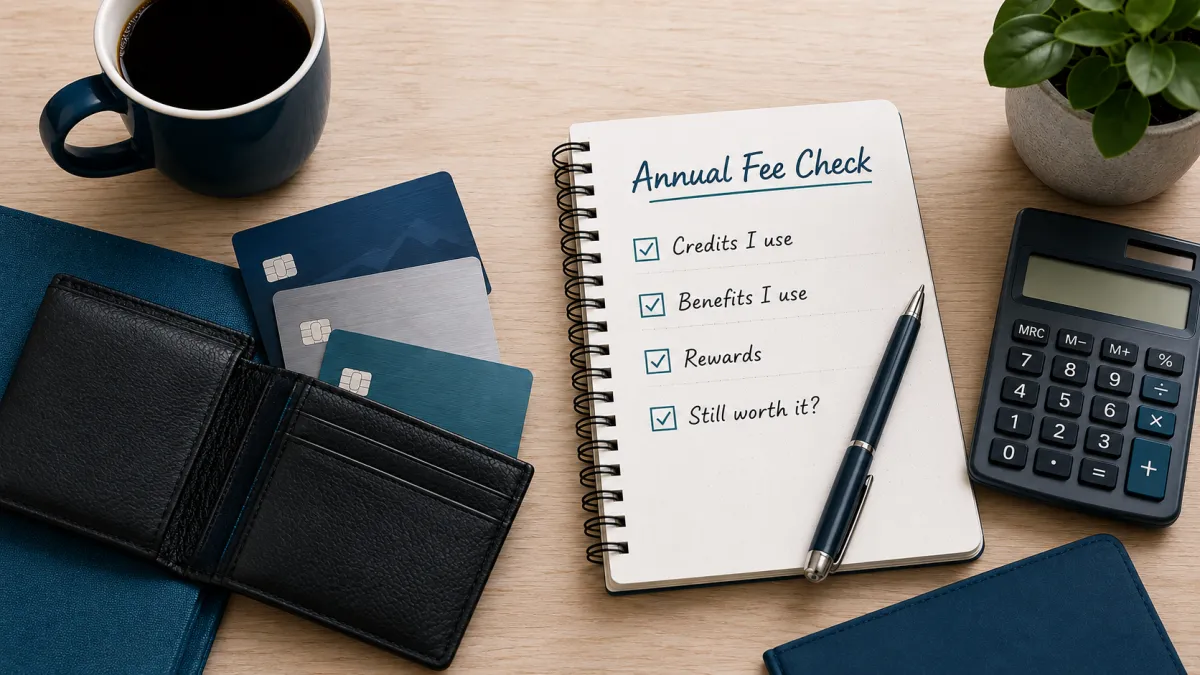
A Simple Annual Fee Check
When an annual fee comes due, ask yourself four questions.
1. What did I actually use?
Look at the credits, benefits, protections, rewards, and perks you genuinely used over the last year.
2. What was that realistically worth to me?
Do not automatically assign every benefit its full advertised value. Think about what it actually replaced or provided for you.
3. Does another card I have already cover the same job?
Look for overlapping benefits, duplicate perks, similar earning categories, and annual fees that may be competing with each other.
4. Would I choose this card again today?
If you were making the decision fresh right now, based on your current spending and goals, would you still want this card in your wallet?
Your Annual Fee Should Support Your Strategy
There is no single annual-fee number where a card suddenly becomes too expensive.
For one person, a no-annual-fee card may be the smartest fit. For someone else, a $95 annual fee may be easy to justify. A much more expensive premium card can also make sense if the benefits, protections, rewards, and actual usage support the cost.
Sometimes the right answer is to keep the card. Sometimes it may make sense to explore a product change or downgrade. Sometimes it may be time to close it, after considering your credit history, rewards balance, and other consequences.
What matters is that the decision fits your current spending, your current goals, and the cards you already have.
That is a much better measure of value than the annual fee alone.
Not Sure Which Cards Are Still Earning Their Place in Your Wallet?
If you have several cards, annual fees, overlapping benefits, or you're simply not sure what is still worth keeping, a Strategy Call gives us time to look at your situation together.
We can talk through what you're using, where you're getting value, where benefits may overlap, and what might be worth reevaluating.
Book a Strategy Call
Strategy Calls start at $79.
If you're mainly trying to figure out what card might fit you next, the free Summit Card Match is another starting point.